Storm Damage Documentation That Adjusters Accept
Insurance Roof Claims Assistance in Saint Charles for homeowners facing hail or wind damage after severe weather events
Insurance claim processes require detailed roof damage documentation that connects storm events to specific shingle failures, flashing separations, or deck damage before adjusters approve repair or replacement coverage. Our Local Roofers LLC inspects roofs after hail storms and wind events, photographs damage patterns that match storm timing, and prepares reports that align with the scope requirements insurance companies use to evaluate claims. The Saint Charles region experiences hail storms and severe wind during spring and summer, though this year saw reduced hail activity compared to prior seasons, which means fewer claims required processing but fall and winter weather still produces damage that surfaces later.
The service involves a detailed roof inspection that documents every damaged area for adjuster review, followed by scope alignment discussions to ensure the insurance estimate covers all necessary repairs. You handle paperwork coordination with your insurance carrier, while the contractor manages settlement review to verify that approved amounts match the work required to restore the roof properly.
Schedule a damage assessment to begin the documentation process before filing your claim.
Our Services
Why Hail Damage Assessment Requires Specialized Knowledge
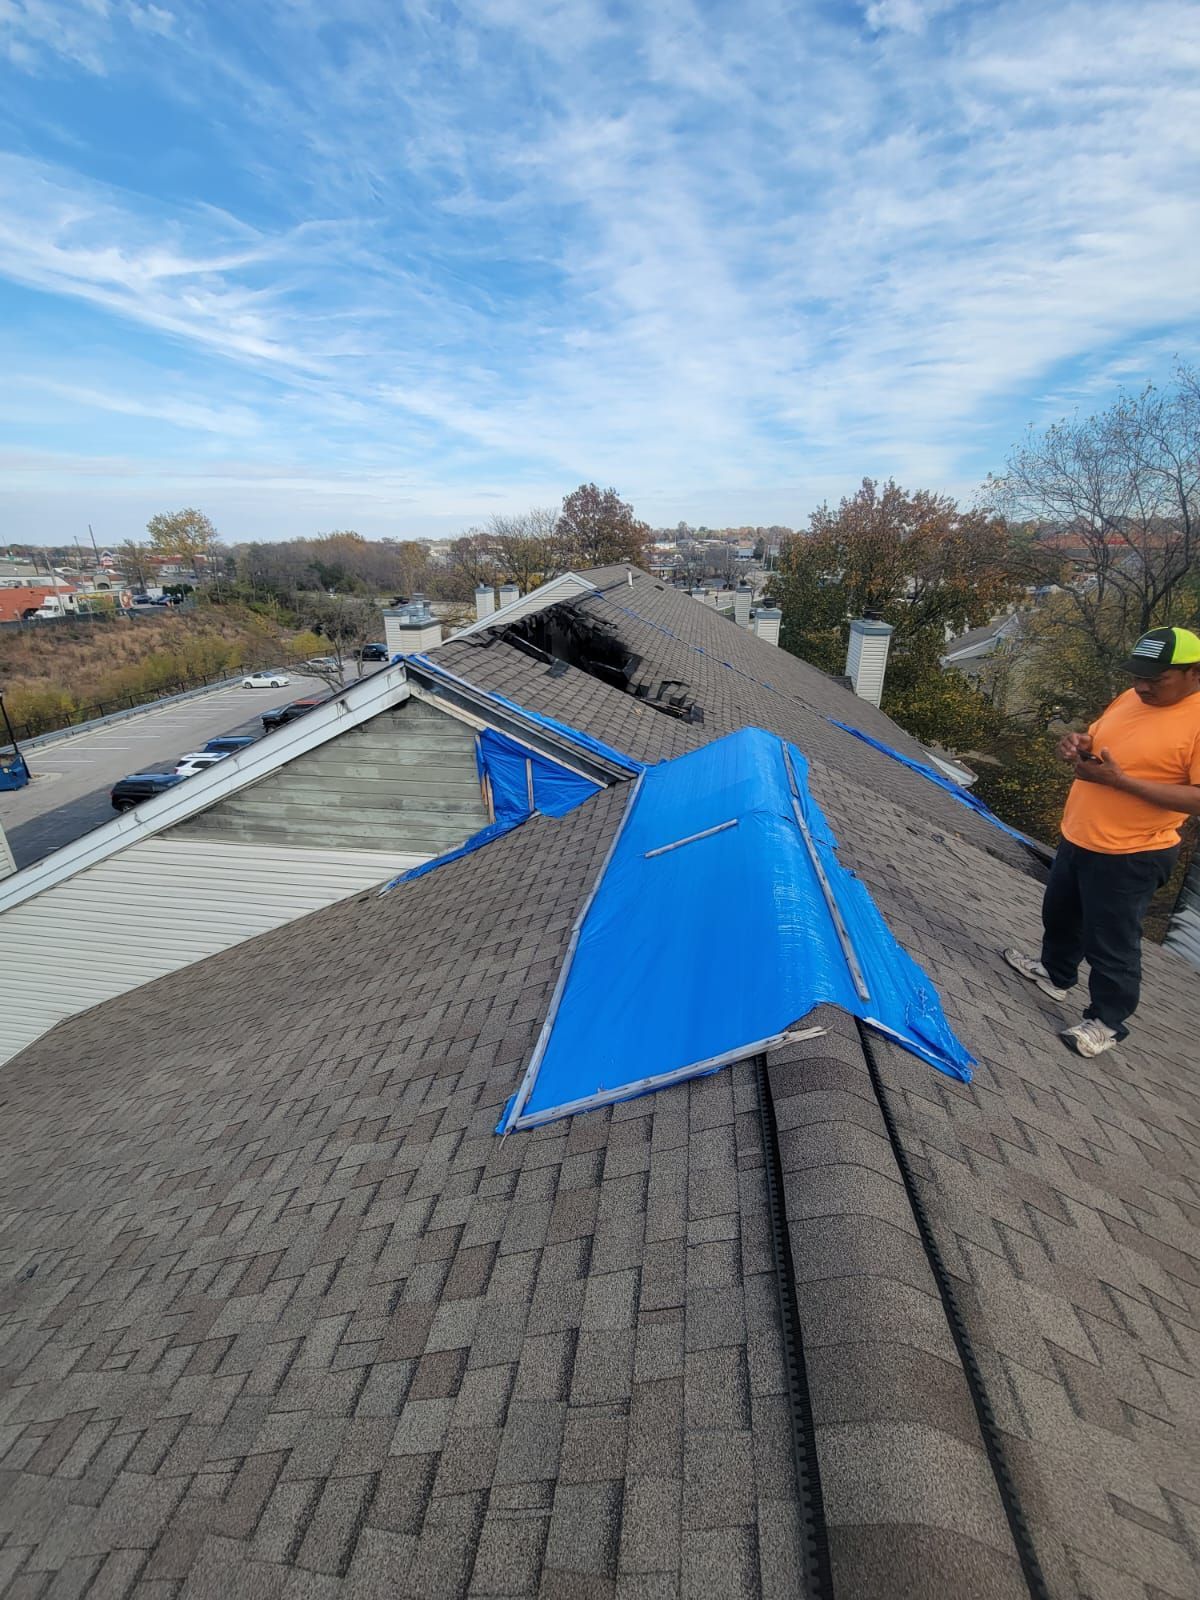
Hail damage assessment starts with identifying impact marks on shingle surfaces, metal flashing, and roof penetrations like vents and skylights, since each material shows damage differently. Asphalt shingles display bruising where granules are dislodged, metal surfaces show denting, and plastic or rubber components may crack or puncture depending on hail size and impact velocity. Seventeen years of roofing experience means recognizing whether damage patterns match recent storm dates or represent older wear, which matters when insurance carriers question whether the claim is storm-related or maintenance-related.
After the inspection is complete and documentation is provided to your insurance company, you receive a scope that outlines which repairs or replacements are covered, and settlement review ensures that the approved amount reflects current material and labor costs. The contractor handles communication about technical details like underlayment replacement and flashing upgrades, while you manage the overall claim filing and approval timeline with your carrier.
The service does not include legal representation if the insurance company denies the claim, and it does not cover non-weather-related damage like aging or improper installation that occurred before the storm. Scope alignment focuses on storm damage only, so pre-existing conditions discovered during inspection are noted separately and may not be covered under the claim.
What Property Owners Usually Ask
Homeowners navigating the insurance claim process for the first time often need guidance on timing and documentation requirements.
How do I know if my roof has hail damage?
Hail damage appears as bruising on asphalt shingles where granules are knocked loose, dents on metal flashing or vents, and cracks on plastic components, and it typically occurs in a random pattern across the roof rather than concentrated in one area.
What does the inspection process include for insurance claims in Saint Charles?
The inspection documents impact marks, photographs damaged shingles and flashing, measures the extent of granule loss, and checks for deck damage visible from the attic, then compiles findings into a report formatted for adjuster review.
When should I file an insurance claim after a storm?
Claims should be filed soon after the storm occurs, ideally within weeks, since delays can make it harder to prove that damage resulted from a specific weather event rather than gradual wear.
Why do insurance adjusters sometimes deny roof damage claims?
Denials often occur when the adjuster determines that damage is due to age or poor maintenance rather than a covered storm event, or when documentation does not clearly connect the damage to a specific date and storm.
What happens if the insurance settlement does not cover all repair costs?
Settlement review identifies gaps between the approved amount and actual repair costs, and you may need to negotiate with the carrier or cover the difference if the policy limits or depreciation adjustments reduce the payout.
Our Local Roofers LLC specializes in hail damage assessment with owner-led inspections that produce the documentation insurance adjusters require to approve claims. Arrange a damage evaluation to begin building your claim file with detailed evidence of storm-related roof damage.